Geely Automobile's Q1 Revenue Surpasses RMB 80 Billion, Regaining Peak Performance
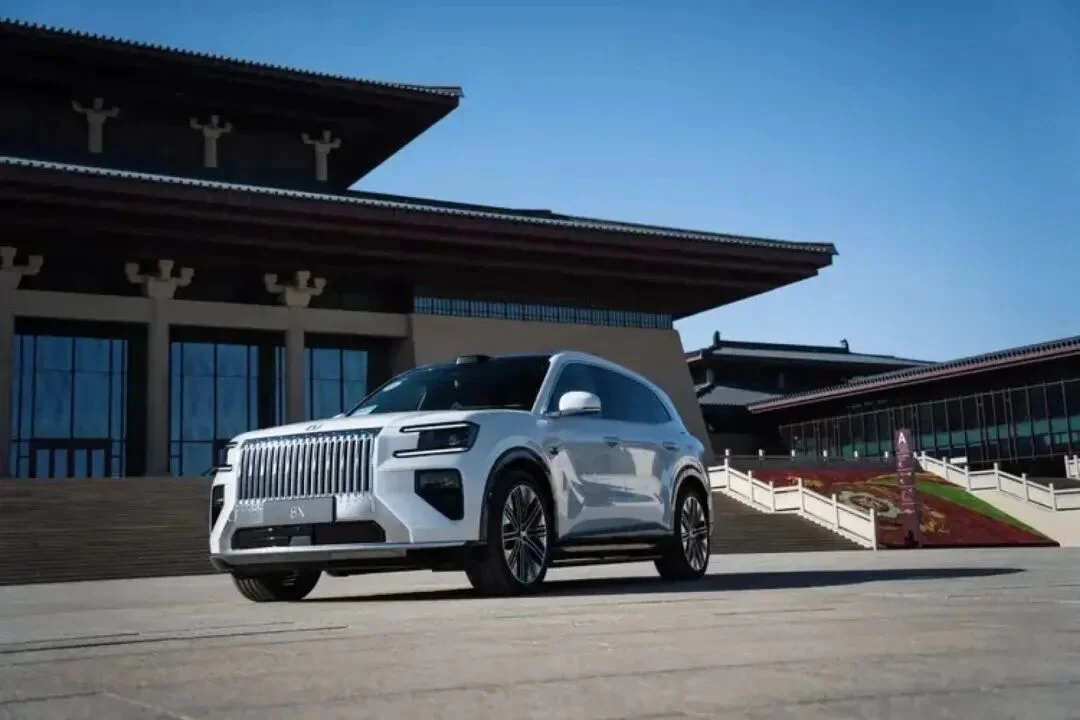
As the leading domestic automaker of the internal combustion engine era, Geely Automobile has delivered its best performance since beginning its new energy transition.
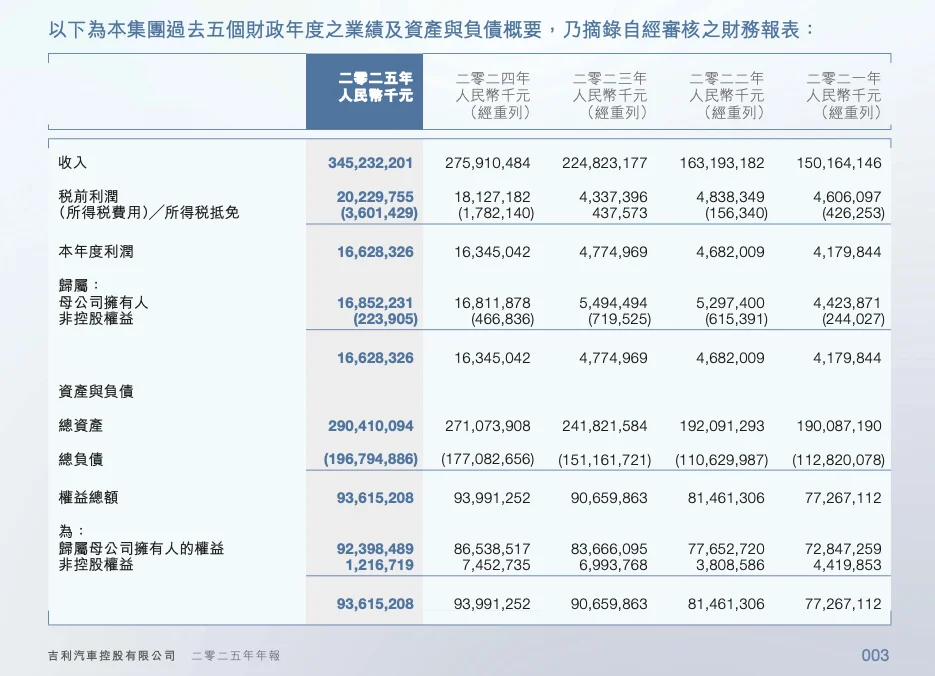
On April 29, Geely Automobile announced during trading hours that it released its financial report for the first quarter of 2026. The report shows that in Q1 2026, Geely Automobile achieved double growth in revenue and profit. Quarterly revenue hit a record high of RMB 83.8 billion, up 15% year on year. After excluding one-off factors such as exchange rate fluctuations and impairment of non-financial assets, the core net profit attributable to shareholders was RMB 4.56 billion, a 31% increase year on year.
Currently, competition in the new energy vehicle market is intensifying. Coupled with high investment driven by technological changes in vehicle architecture, chassis, powertrains, chips, and autonomous driving, most Chinese automakers are trapped in the dilemma of "increasing volume without increasing revenue, and increasing revenue without increasing profit." Seres, which released its earnings report on the same day as Geely, failed to break this curse despite strong backing from Huawei. Its net profit excluding non-recurring items for the first quarter was only RMB 103 million, a sharp drop of 74% year on year.
Several other automakers that disclosed their results earlier also faced grim conditions. Changan and Great Wall Motor, once known alongside Geely as the "Top Three Domestic Automakers," saw all three core indicators—sales volume, revenue, and net profit excluding non-recurring items—decline across the board. Although Great Wall Motor's revenue grew by 13%, its net profit excluding non-recurring items fell 67% year on year to RMB 480 million, far below market expectations. Consequently, it has had its earnings forecasts or target prices downgraded by multiple institutions, including CICC.
According to the latest data from the National Bureau of Statistics, the overall sales profit margin of the automotive industry in Q1 2026 dropped to 3.2%, hitting a historical low. Now even the industry leader BYD is under pressure. In Q1 2026, BYD reported total revenue of RMB 150.2 billion, higher than the Bloomberg consensus estimate of RMB 140.4 billion, but down 12% from the same period last year. Its net profit excluding non-recurring items was RMB 4.15 billion, a 49% decrease year on year.
In comparison, Geely Automobile's performance stands out. Notably, this is the first quarterly earnings report after Zeekr delisted from the US stock market and completed integration with Geely Automobile. Guided by the "One Geely" strategy, multiple brands within the Geely group worked together to achieve a total sales volume of 709,000 units in the quarter, surpassing BYD and reclaiming the title of China's top-selling domestic brand for the first time in four years.
"The record-high performance in the first quarter is just the beginning," Gui Shengyue, Executive President and Executive Director of Geely Automobile, stated at the earnings conference. He noted that through integration, Geely Automobile has achieved full coverage of various energy forms and market segments. Geely has now entered a new cycle of high-quality development. This is not only true domestically but more importantly internationally; Geely Automobile will be the first to break through, comprehensively changing the international image of Chinese automobiles.
01One Geely: A Traditional Auto Giant’s Transformation Model
It is hard to imagine that just over a year ago, Geely—now claiming to represent Chinese automobiles refreshing their international image—was struggling with transformation and going global.
Fast forward to September 1, 2024. Under the leadership of founder Li Shufu, all management personnel from the Geely Group returned to Taizhou, where Geely Automobile’s journey began, to revisit their entrepreneurial history. On September 20, Li Shufu released the "Taizhou Declaration" externally, launching a new round of strategic transformation for Geely. The company announced a shift from strategic expansion to strategic focus and integration, closing or merging certain business units, while emphasizing steady operations and avoiding blind expansion.
This marks another critical turning point in Geely’s automotive history.
As a private automaker founded in Taizhou, Geely’s path in car manufacturing can roughly be divided into three stages. For the first decade after entering the auto industry in 1997, it was largely a period of exploration and startup. After successfully listing on the Hong Kong Stock Exchange in 2006, it embarked on global capital expansion. Notably, through its acquisition of Volvo in 2010, it gradually mastered the intricacies of carmaking, eventually surpassing Changan to become the sales champion among domestic brands in 2017.
However, after ascending to the top spot among independent brands and joining the million-unit sales club, Geely gradually entered a bottleneck period. In 2018, Geely’s sales hit a record high of 1.5 million units, but the growth rate dropped by 45.7 percentage points. Thereafter, overall sales gradually fell back to around 1.3 million units. From 2018 onward, Geely failed to meet its predetermined sales targets for five consecutive years.
A significant background factor is that the entire automotive market entered an adjustment phase during this period. From 2018 to 2020, China’s auto market experienced negative growth for three consecutive years, only stabilizing gradually in 2021. As a result, competition among automakers intensified, and price-cutting strategies to boost volume became commonplace. Consequently, Geely’s profit per vehicle declined from RMB 8,445 in 2018 to RMB 3,275 in 2021.
Indeed, this period represented a golden window for the rise of new energy vehicles. From 2018 to 2020, the first wave of EV startups—commonly referred to as "Wei-Xiao-Li" (NIO, XPeng, and Li Auto)—listed in the United States one after another. Meanwhile, second-tier players like Leapmotor and Neta began to emerge, while traditional automakers launched their own explorations into new vehicle-building models. Aion, Voyah, and Avatr followed suit, and BYD successfully completed its technological iteration from e-Platform 1.0 to 3.0.
During the same period, the market penetration rate for new energy vehicles climbed rapidly. According to data from the China Association of Automobile Manufacturers (CAAM), domestic new energy vehicle penetration reached 5.4% in 2020.
Geely, which had launched a transformation plan as early as 2015, failed to capitalize on this dividend of new energy vehicle development. In 2018, Geely’s new energy vehicle sales totaled 68,500 units, with a penetration rate of 4.6%. By 2020, however, sales did not increase but instead declined slightly to 68,000 units, corresponding to a penetration rate of 5.2%. This fell far short of the target set by its initial "Blue Geely" plan, which aimed for a 90% penetration rate by 2020.
Faced with this gap, Geely once again unveiled its "Smart Geely" plan in 2021, deciding to invest RMB 150 billion over 5 years and launch at least 25 new energy vehicles. Geely also concentrated its bets on two vehicle-making ventures, Zeekr and JIDU, and announced plans to accelerate Volvo's transition to electric vehicles. Geometry, whose attempts to move upmarket had stalled, also began adjusting its positioning. Yet these efforts yielded little: Geely's new energy vehicle sales fell further to 61,000 during that period.
Thereafter, Geely continued to ramp up talent acquisition and accelerate its diversified layout in the new energy sector. Technologically, it bet heavily across multiple routes, including pure electric, hybrid, battery swapping, and methanol powertrains. Brand-wise, it established numerous independent sub-brands: Geometry, Lynk & Co, Geely, Zeekr, Maple, LIVAN, Volvo, smart, and Lotus. In 2023, Geely incubated the micro-EV brand Panda and the mid-to-high-end brand Galaxy.
This multi-pronged approach gradually dispersed Geely’s transformational focus. Ultimately, only a few brands, such as Zeekr, Lynk & Co, and Galaxy, managed to break through. However, none of these three achieved true leadership within their respective market segments. Moreover, overlapping positioning led to internal friction among them. For instance, both Lynk & Co and Zeekr, which already held similar positions in the market segment above RMB 200,000, simultaneously deployed both pure electric and hybrid models.
Meanwhile, Geely’s multi-brand, full-ecosystem industrial layout also means massive resource investment. Take the case of a new brand built from 0 to 1 by Geely: in just three years from 2021 to 2023, Zeekr’s cumulative losses exceeded RMB 13 billion. In response, the Geely group has been continuously using business spin-offs and listings for capital maneuvering, but after independent listings, brands such as Zeekr, Polestar, ECARX, and Lotus have mostly seen poor market performance.
Furthermore, following these spin-off listings, subsidiaries like Zeekr were subject to independent accounting requirements as listed entities, making it difficult to achieve comprehensive synergy with the broader Geely group. Duplication in research and development and channel construction resulted in significant waste. Additionally, when facing market risks, these sub-brands often lacked sufficient strength. For example, Zeekr, which had originally planned to expand its overseas sales volume in 2024, was forced to slow down due to EU tariff policies.
Until Geely Automobile refocused its strategy in 2024, it had not achieved a genuine breakthrough in its new energy transition.
In 2023, Geely Automobile’s total sales volume for its entire lineup reached 1.687 million units, a year-on-year increase of 18 percent. During the same period, BYD’s sales scale had already exceeded 3 million units, with a year-on-year growth rate of 62 percent. While overall performance lagged behind leading automakers, Geely’s new energy vehicle (NEV) sales amounted to only 487,000 units, resulting in an NEV penetration rate that was seven percentage points lower than the market average. Its overseas sales volume and growth rate also fell significantly short of competitors such as Chery, SAIC, and Great Wall Motor.
More importantly, the industry has reached a consensus that the 2025 auto market finals are imminent, meaning the window of time for Geely to maneuver is narrowing.
In September 2024, after Li Shufu issued the Taizhou Declaration, businesses within the Geely group rapidly consolidated their efforts with the goal of rebuilding “One Geely.”
On the brand front, Geely conducted a restructuring benchmarked against Volkswagen. It first merged Zeekr and Lynk & Co, then brought brands such as Geometry and LEVC under Galaxy. In August last year, it initiated the privatization of Zeekr to integrate it with Geely Automobile. Currently, Geely’s brand positioning in the new energy market is as follows: Galaxy targets the mainstream consumer market below RMB 200,000, focusing on volume and scale expansion; Lynk & Co and Zeekr respectively target the high-end and luxury markets to enhance brand premium.
Accompanying the brand integration, Geely also implemented a series of personnel adjustments. The restructured Geely Automobile is coordinated by former Geely Automobile CEO Gan Jiayue, who oversees two major business divisions: Galaxy and Zeekr. Gan Jiayue directly leads the Galaxy division, while An Conghui, former CEO of Zeekr, manages the Zeekr division. An Conghui also serves concurrently as Group CEO, while former Group CEO Li Donghui was promoted to Vice Chairman of the Board, responsible for daily board management and investment and financing.
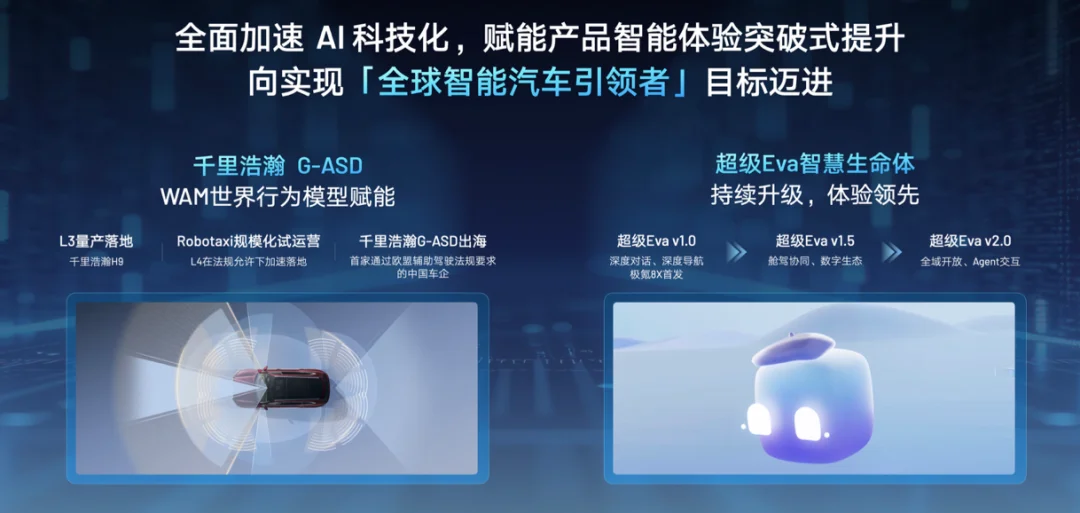
On the business front, Geely systematically integrated seven core areas: vehicle mechanical architecture, electronic and electrical architecture, intelligent driving, cockpit systems, electric drive systems, power batteries, and super hybrid technology, thereby unifying the product technology foundation across all brands. To quickly elevate its intelligence standards, Geely also introduced external forces such as Yin Qi to establish a joint venture, Qianli Technology. In March last year, it launched five sets of intelligent driving solutions to compete directly with BYD’s God's Eye.
This series of integrations gradually came to an end last December when Zeekr was officially delisted from the US stock market. In 2025, Geely, which is undergoing deep integration, has already begun to show its sharp edge. Most of its segments, including Geely, Volvo, Polestar, Proton, and Farizon, have achieved growth amid fierce market competition. The cumulative sales for the year reached 4.116 million units, a year-on-year increase of 22%, significantly outperforming the broader market, among which Geely Automobile's growth rate reached 39%.
The penetration rate of new energy vehicles also reached a new milestone. In 2025, Geely Xingyuan, which targets A0-segment compact cars like BYD’s Dolphin and Yuan UP, sold 470,000 units, becoming the top-selling model across all categories in China. Driven by hit models such as Xingyuan, Geely’s new energy vehicle sales grew 90% year-on-year to 1.688 million units, accounting for 56% of total sales—an increase of more than 15 percentage points compared to the previous year.
At the beginning of this year, against the backdrop of domestic auto growth showing signs of peaking, Geely announced a plan for average annual growth of 10% over the next five years and claimed it aims to enter the global top five in sales by 2030.
An Conghui, CEO of Geely Group, analyzed that new energy vehicles and overseas markets will be Geely’s two main growth drivers. By 2030, Geely aims for a new energy penetration rate of 75% and an overseas sales share of one-third. Gan Jiayue, CEO of Geely Automobile, clarified short-term goals during the subsequent annual report briefing: Geely plans to sell 3.45 million vehicles in 2026 and surpass BYD to reclaim the title of China’s best-selling automaker.
02Two Keywords for the New Geely: Premiumization and Internationalization
As the most successful transformation example among traditional automakers, Geely is gradually realizing its performance targets.
In Q1 2026, Geely surpassed BYD with total sales of 709,000 vehicles, becoming the sales champion among domestic brands. Its subsidiaries contributed 312,000 units (Geely), 239,000 units (Galaxy), 82,000 units (Lynk & Co), and 77,000 units (Zeekr). Lynk & Co 10 EM-P took the sales crown in China’s B-segment hybrid market, while three Galaxy models—Xingyuan, Galaxy M9, and Xingyao 8—each became the top sellers in their respective segments.
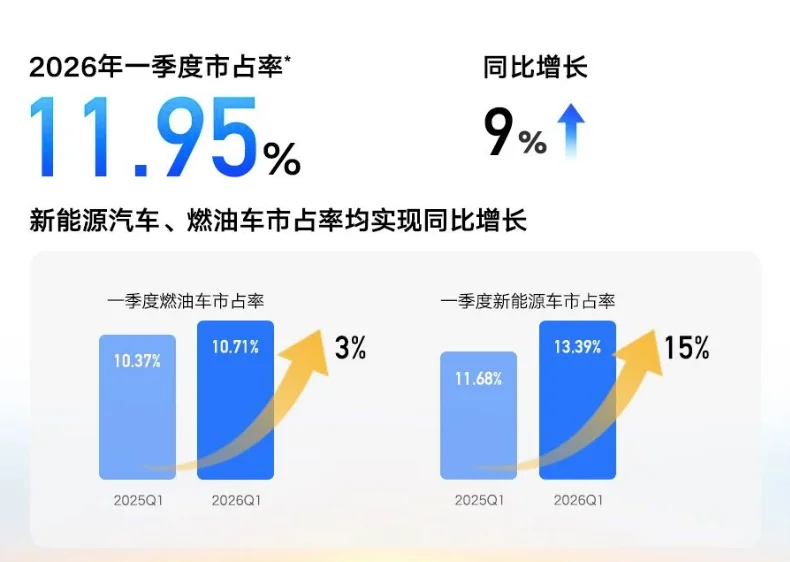
Driven by blockbuster models, Geely’s new energy vehicle sales reached 369,000 units in Q1 2026, up 9% year-on-year. During the same period, due to the phase-out of purchase tax incentives and seasonal factors, domestic new energy vehicle sales fell 23% year-on-year to 1.802 million units. Based on these figures, Geely’s share of the new energy market reached 20.5%, second only to BYD and ranking as the second-best-selling brand among domestic automakers.
The automotive industry is a game of extreme scale. In Q1 2026, Geely achieved record-high revenue of RMB 83.8 billion, building on its peak production volume. After excluding parts and technology licensing income, the average selling price per vehicle reached RMB 112,000, an increase of approximately RMB 20,000 year-over-year. This drove the overall gross margin to 17.5%. For comparison, Tesla and BYD reported automotive gross margins of 19.2% and 16.8%, respectively, in the same period.
"We do not rely on price wars for market competition; instead, we build core competitiveness through brand synergy, technological integration, product quality, and service," Gui Shengyue stated at the earnings call. He noted that Geely’s various brands have integrated to share underlying technologies, production capacity, and sales channels. This significantly reduces manufacturing and operational costs. By concentrating efforts externally across multiple brands, the overall brand effect has strengthened, with signs of premiumization and international expansion beginning to emerge.
According to management, under the new integrated architecture, Geely’s average R&D cycle per vehicle and comprehensive costs have decreased by more than 30%.
"Q1 gross margins have already shown strong performance," said Dai Yong, CFO of Geely Automobile. He explained that while the pace of cost reduction from integration was slower last year—meaning Geely’s margin potential had not yet been fully realized—the integration was largely complete in Q1 this year, with cost-reduction targets nearly 80% met. Consequently, future margin space will continue to expand. However, he emphasized that recent price increases in upstream raw materials such as lithium carbonate would create some pressure, estimated to have a negative impact of around RMB 2,000 per vehicle.
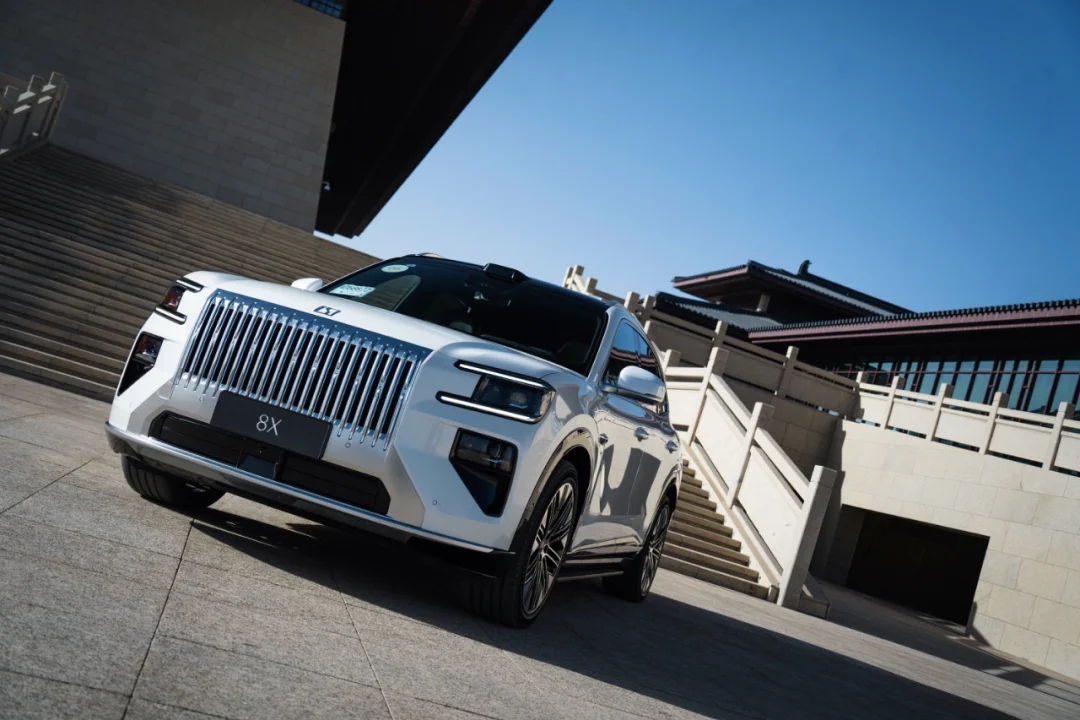
In terms of premiumization, Zeekr is the primary driver lifting Geely’s average selling price. Management disclosed that in Q1 2026, Zeekr’s average selling price reached RMB 295,000, up from RMB 281,000 in the same period last year. The flagship model, Zeekr 9X, had an average transaction price of RMB 530,000 and has delivered over 10,000 units for three consecutive months. The newly launched Zeekr 8X also exceeded an average transaction price of RMB 400,000, with more than 10,000 confirmed orders placed within half an hour of its launch.
Gan Jiayue revealed that at Geely’s recent overseas dealer conference, the Zeekr 8X and 9X attracted attention among more than 1,400 dealers.
Starting in 2024, Geely Automobile has been aggressively advancing its new energy vehicle (NEV) exports, although the two aforementioned models have not yet been officially launched overseas. He stated that both the styling and the powertrain performance and driving dynamics have impressed a number of overseas dealerships. Currently, the 8X and 9X are being sold at premiums abroad, with prices reaching as high as RMB 1.1 million. While he did not disclose the target pricing for these two models in overseas markets, he emphasized that gross margins will be significantly higher than those in China.
In terms of overseas market layout, Geely once gained an early advantage through investments, mergers and acquisitions, technology equity stakes, and joint venture factories. However, it has gradually fallen behind in this wave of export growth driven by domestic NEVs, recording only 184,000 exported vehicles in the first half of 2025. Subsequently, Geely accelerated its efforts to catch up, speeding up product internationalization and partnering with Renault to leverage the latter’s factory and dealership network in Brazil for an asset-light export strategy.
Different from automakers like BYD that build their own factories overseas, Li Shufu believes that global automotive production capacity is generally oversupplied. He stressed that Geely should avoid building its own factories when going global, instead sharing capacity with joint venture partners to achieve localized production—for example, using Proton’s facilities in Southeast Asia and Renault’s plants in Brazil. Industry observers believe this model helps Geely expand overseas and close the gap with competitors, but its operational efficiency and management capabilities may face tests.
To date, Geely has covered more than 100 countries and regions through its asset-light model, with over 1,900 global sales and service outlets. Focusing on the UK market, where brands such as Lotus, London Electric Vehicle Company (LEVC), and Manganese Bronze Holdings are based, Geely aims to establish a foothold there. It is targeting four major markets of 150,000+ units each—Europe, Eastern Europe, ASEAN, and Latin America—as well as a Central Asian market of 100,000+ units, striving to reach an annual export target of 750,000 vehicles.
In its overseas strategy, Geely has also drawn lessons from peers like BYD, gradually introducing domestically proven hit models to international markets, including the Geely Xingyuan, Xingjian 7 EM-i, Lynk & Co 01, and Lynk & Co 02. Among them, the Geely Xingyuan, launched overseas under the name EX2, has gained popularity in multiple markets such as Brazil, Indonesia, and Thailand, consistently ranking at the top of the pure electric small car sales charts in Indonesia and Thailand for consecutive months.
In the first quarter of 2026, Geely’s total overseas sales exceeded 200,000 units, representing a year-on-year growth of 126%, with NEV exports surging by 572%.
Overall, while Geely Automobile’s overseas expansion is growing rapidly, its export scale still lags considerably behind leading automakers such as Chery and BYD. Gui Shengyue analyzed that this is mainly because Geely’s NEV export journey started later and its overseas model matrix is not yet fully developed. As the structure of exported models optimizes and scale increases, Geely is expected to become one of the Chinese automakers with the most rational overseas layout and strongest profitability.
The industry generally believes that there is about a three-year gap in NEV adoption between China and overseas markets. However, Geely’s management does not expect such a long window, judging that the gap will align within at most one to two years. To improve overseas operational efficiency, Geely has already reformed its channels abroad, transitioning from general agents to subsidiary operations. Next, Geely hopes to accelerate the launch of new products overseas and seize the remaining golden window of opportunity.
According to its plan, Geely’s Zeekr 9X will launch in the Middle East by late June, with expansion to Europe and other regions following in September.
However, Geely, standing at a new starting point for high-end positioning and internationalization, is not out of the woods.
On one hand, Geely’s comeback against BYD in China was largely driven by hit internal combustion engine (ICE) models such as Boyue L and Xingyue L. The overall ICE market has entered an irreversible decline. As giants like BYD, CATL, and Tesla continue to invest heavily in charging networks, ultra-fast charging technology, and battery products, the irreplaceability of ICE vehicles will weaken further. Whether Geely can sustain its sales advantage remains to be seen.
On the other hand, in Q1 this year, Geely’s main competitor BYD was in a transition period between old and new products, making it relatively weaker. With major technologies such as the next-generation Blade Battery and megawatt-level flash charging, BYD is set to launch a dense lineup of new models, including Datang and Dahan from the Dynasty series, Ocean series 06 and 08, the updated Denza D9, Denza Z, and Fang Cheng Bao Titanium 7. Geely will face greater competitive pressure.
Furthermore, the Chinese domestic and overseas markets are essentially interconnected. In mainstream export destinations such as Thailand, Indonesia, the Middle East, and Europe, Geely’s closest rivals remain Chinese automakers like BYD, Chery, and Great Wall Motor. Many of these target markets have seen EV demand gradually saturate. As a latecomer, Geely must engage in fiercer competition with fellow Chinese brands to establish a foothold overseas.
Whether Geely, after restructuring, can navigate the extreme challenges of the automotive industry, pass every hurdle, and reach the global top five, time will tell.
Written by: Florence Edited by: James