Leapmotor Says Goodbye to 'Mini Li Auto' Label
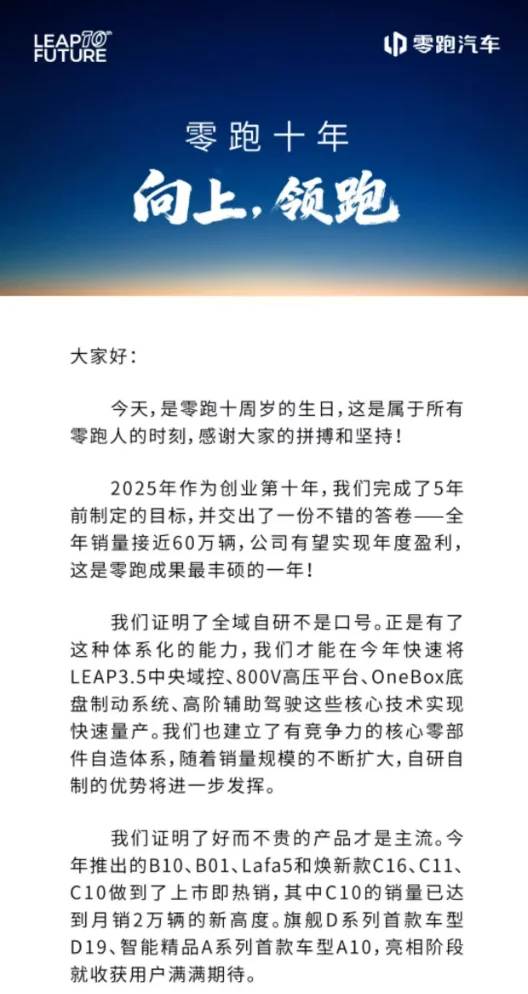
Today marks Leapmotor’s 10th anniversary. With annual sales nearing 600,000 units and profitability for the year in sight, founder Zhu Jiangming defined this year as “Leapmotor’s most fruitful year” in an internal letter released today.
Looking at a longer timeline, this year has been not only productive for Leapmotor but also a critical watershed moment.
For years, the outside world viewed it as a follower of Li Auto, even summarizing its product strategy with the label “Little Li Auto.” But by this year, that tag began to feel inaccurate. It no longer needed to “imitate” Li Auto; it had firmly established its own footing.
Starting from the third quarter of this year, Leapmotor achieved consecutive quarterly profits, with cumulative net profit reaching RMB 180 million in the first three quarters. In November alone, it delivered 70,327 vehicles, marking nine months of continuous growth and allowing it to complete its beginning-of-year target of 500,000 annual sales ahead of schedule. A car company that once struggled on the brink of survival and was later seen as an imitator suddenly began to show the momentum characteristic of a top-tier player.
At this point, people realized that “imitation” may have merely been a smokescreen that won it entry into the arena. What truly reshaped its growth curve were capabilities that were invisible on the surface.
When a company uses imitation to establish its footing and then leverages innovation and systemic efficiency to open up a new growth curve, it truly begins to become itself. Leapmotor in 2025 is precisely at such an inflection point.
Next year, Leapmotor aims to achieve a net profit of RMB 5 billion on the foundation of reaching one million annual sales.
In an internal letter released today, Zhu Jiangming stated that the past decade was a period of near-extinction and that Leapmotor has only just reached the subsistence level, far from the time for celebration. "We can no longer identify ourselves as 'new forces'; we must hold ourselves to the standard of a sustainable, respectable world-class automaker."
Moving away from being labeled a 'mini Li Auto' or a 'new force,' aiming for annual sales of one million units, and striving to become a 'world-class automaker': how far is Leapmotor still from these goals?
01Leapmotor Has Moved Past Its 'Imitation Phase'
If you rewind to 2024, Leapmotor indeed bore many similarities to Li Auto.
The C10 and C16, which later became the volume drivers for Leapmotor, followed paths already validated by Li Auto's L7 and L8 models in terms of size, product positioning, and the choice of an extended-range electric vehicle (EREV) strategy.
This included the sizing orientation of mid-to-large SUVs, spatial narratives centered on family users, a technology route focused on EREVs, comfort features such as refrigerators, large screens, and plush sofas, and marketing messaging that emphasized second-row experience and long-distance travel scenarios.
For Leapmotor at that time, this product strategy was pragmatic and reasonable. It helped the company emerge from the lukewarm performance of the C11, C01, and T03, avoiding the fate of becoming an obscure player.
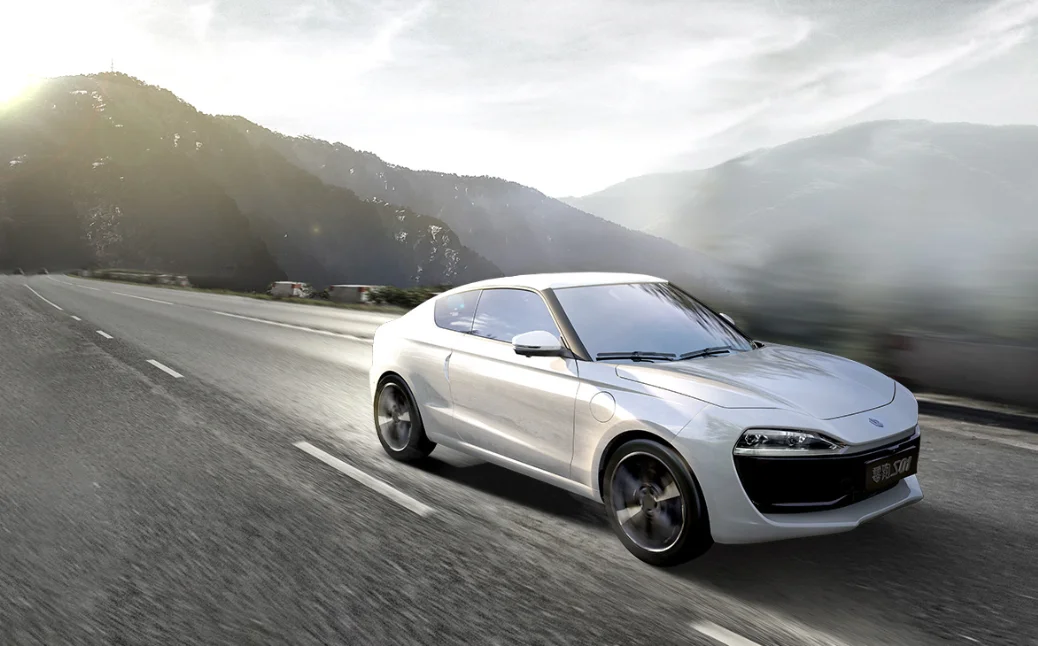
Before the launch of the C10 and C16, Leapmotor's situation was not as smooth as it later became. Ten years ago, when the company was just starting out, it was inconspicuous. The first dual-door coupe, the S01, launched in 2019, did not achieve immediate success; its sales hovered in the triple digits for a long time before it quietly exited the market.
In 2020, Leapmotor relied almost entirely on its sub-100,000 RMB T03 to sustain monthly sales of just over 3,000 units. The C11’s launch in 2021 marked the brand’s true entry into the mainstream 100,000–200,000 RMB segment. Sales briefly exceeded 10,000 units in 2022, suggesting a stable trajectory, but a cliff-like drop followed in early 2023 when Leapmotor failed to follow industry-wide price cuts and instead raised prices, causing monthly volume to plummet from around 10,000 to just over 1,000.
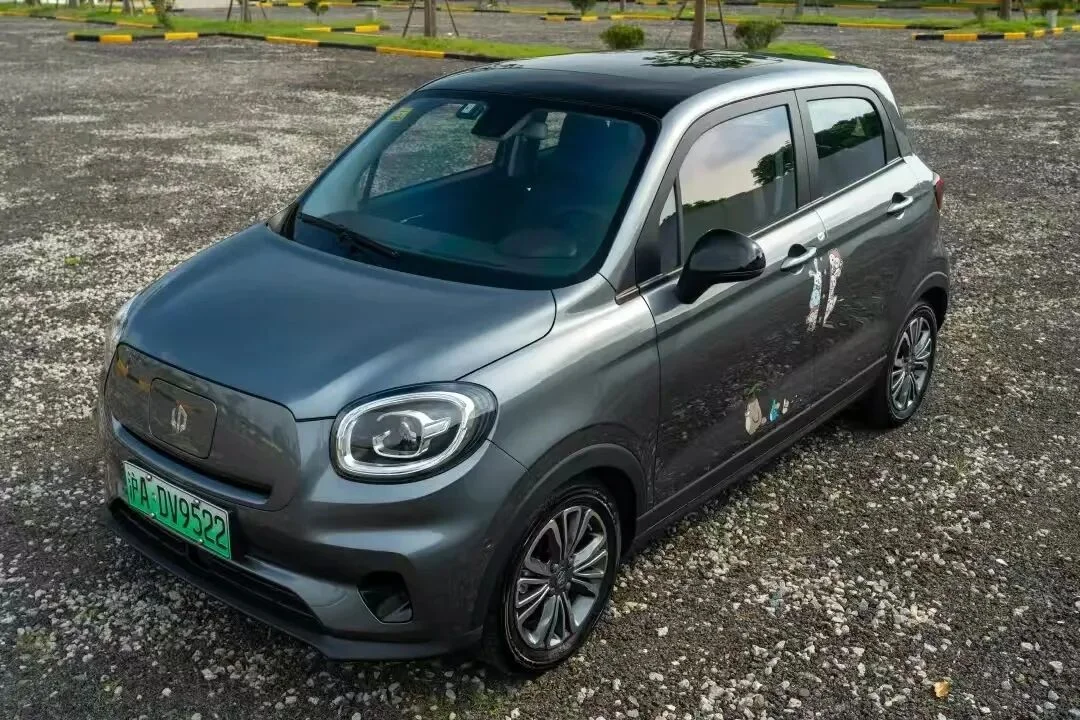
The company adjusted quickly. By late 2023, a repaired product lineup helped Leapmotor regain monthly deliveries of 18,000 units. However, brand momentum remained weak, and the product images of the C11 and C01 had not yet been fully established. From 2021 to 2023, the company experienced repeated fluctuations—rising from hundreds to thousands, then to ten thousand, before falling back to the bottom—without ever forming a stable growth curve.
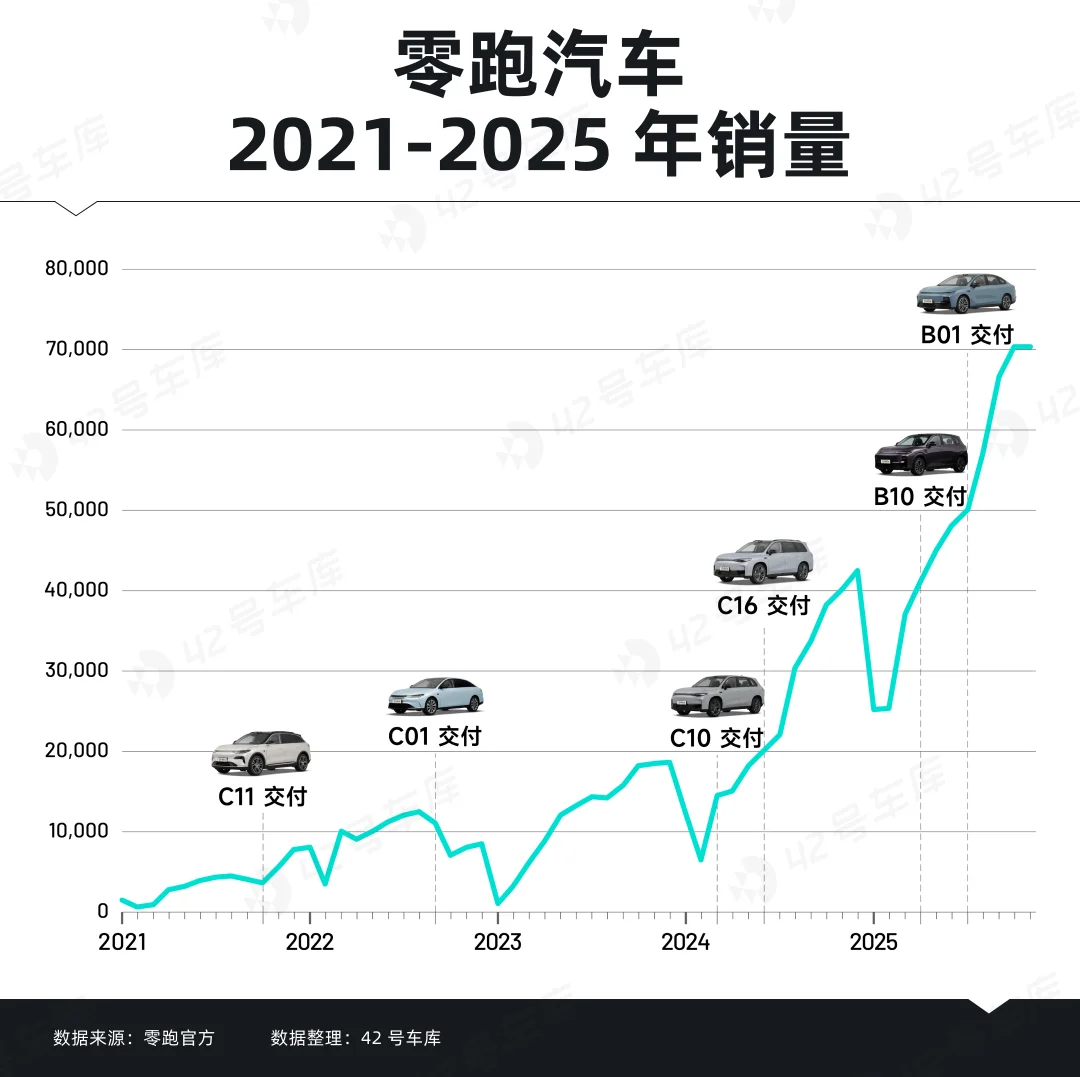
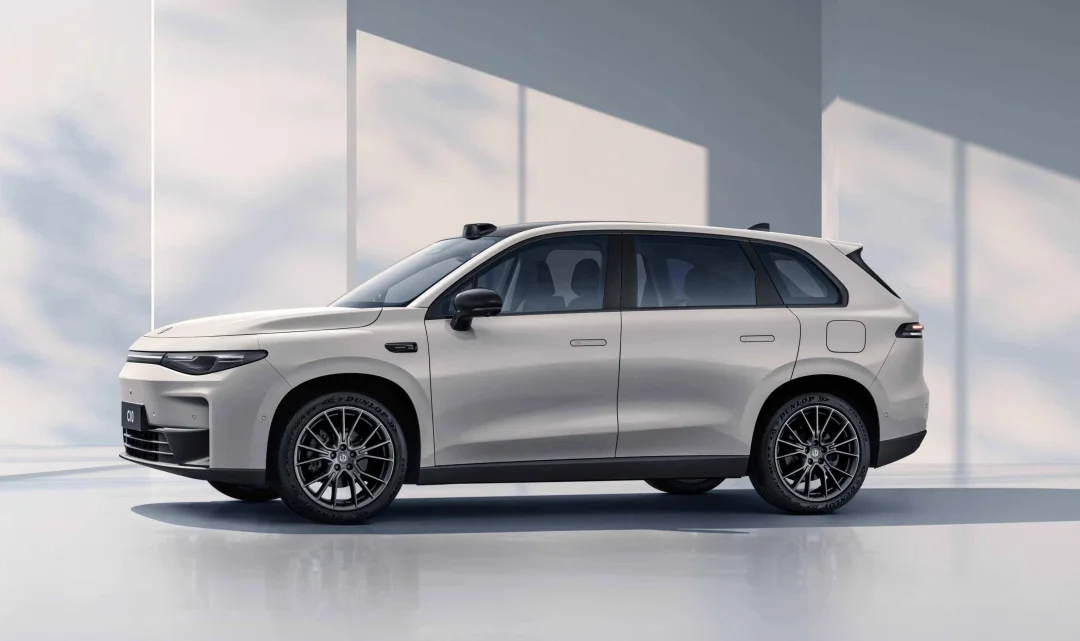
The real turning point came with the successive launches of the C10 and C16 in 2024. These were Leapmotor’s first mature mainstay models capable of sustaining steady volume increases.
The impact on sales was nearly immediate. Following the C10’s launch in February 2024, Leapmotor’s monthly delivery volume, which had hovered around 10,000 units, quickly surged to near 30,000. With the C16 joining the lineup mid-year, that figure officially broke the 30,000-unit mark, pushing Leapmotor’s monthly sales to 40,173 by the end of 2024—a height the brand had never previously reached.
Consequently, the nickname “Little Li Auto” became widespread at the time. Leapmotor executives did not reject the comparison. At the 2024 Guangzhou Auto Show, Cao Li, Senior Vice President of Leapmotor, stated in an interview that while the company does not mind the “Little Li Auto” moniker, it also does not wish to be labeled as such; Leapmotor remains Leapmotor.
In the logic of technology-driven consumer goods, a vast chasm separates early adopters from the early majority. Failing to bridge it means failure. For a new company without a blockbuster model to its name, breaking into a new market and catching the eye may not be difficult, but creating products accepted by the mass market is hard. Walking a proven path was then the easiest way for Leapmotor to cross the threshold of user distrust.
Perhaps only those who have tasted failure understand that seeking expansion is less prudent than seeking stability. This mindset became ingrained in Leapmotor’s DNA, influencing its later decisions on technical routes such as intelligent driving.
History proved this strategy highly effective at the time. "Imitation" served as a passport to the mainstream market, moving freely in China’s market, which naturally welcomes "affordable alternatives." The C10 and C16 transformed Leapmotor from a peripheral player into many users’ top choice almost overnight. They quickly established themselves in the RMB 100,000–200,000 price segment, capturing family users that Li Auto could not reach.
Sales trends tell the story: entering 2025, Leapmotor recorded nine consecutive months of growth, with November deliveries exceeding 70,000 units. Over a longer timeline, the C10 and C16 became key milestones driving Leapmotor’s volume from thousands to tens of thousands of units.
However, the monthly sales trajectory following the launch of the C10 and C16 also reveals that while imitation lowered the cost of brand understanding for consumers, actual sales growth relied on Leapmotor’s own product strength and reputation.
Yet, starting in 2025, the relationship between Leapmotor and Li Auto underwent a fundamental shift. As configurations and product routes that attract users are no longer secrets, competition in the new energy vehicle industry has quietly shifted from choosing product strategies to competing on efficiency, scale, and globalization. Imitation cannot replicate systemic capabilities. It was at this stage that Leapmotor’s growth trajectory began to diverge from Li Auto’s.
The most typical example is the surge in sales of B-series pure electric sedans. Li Auto never entered this segment, yet Leapmotor turned a pure electric sedan into a blockbuster in the fiercely competitive RMB 100,000–120,000 range, where cost structure is most critically tested. The B-series achieved monthly sales of 24,000 in September, accounting for nearly 40% of total sales. Launched in July, the B01 sold 12,600 units in September alone; by December 1 this year, cumulative deliveries of the Leapmotor B01 had exceeded 60,000 units. This is not a result that imitation can produce.
The differences between Leapmotor and Li Auto in their globalization paths are equally pronounced. Li Auto previously wavered on its overseas strategy, relying mainly on parallel exports; as policies tightened recently, its overseas sales have dropped significantly. This year, after finally clarifying its direction for going global, Li Auto completed its layout in four overseas markets and established R&D centers in Germany and the United States.
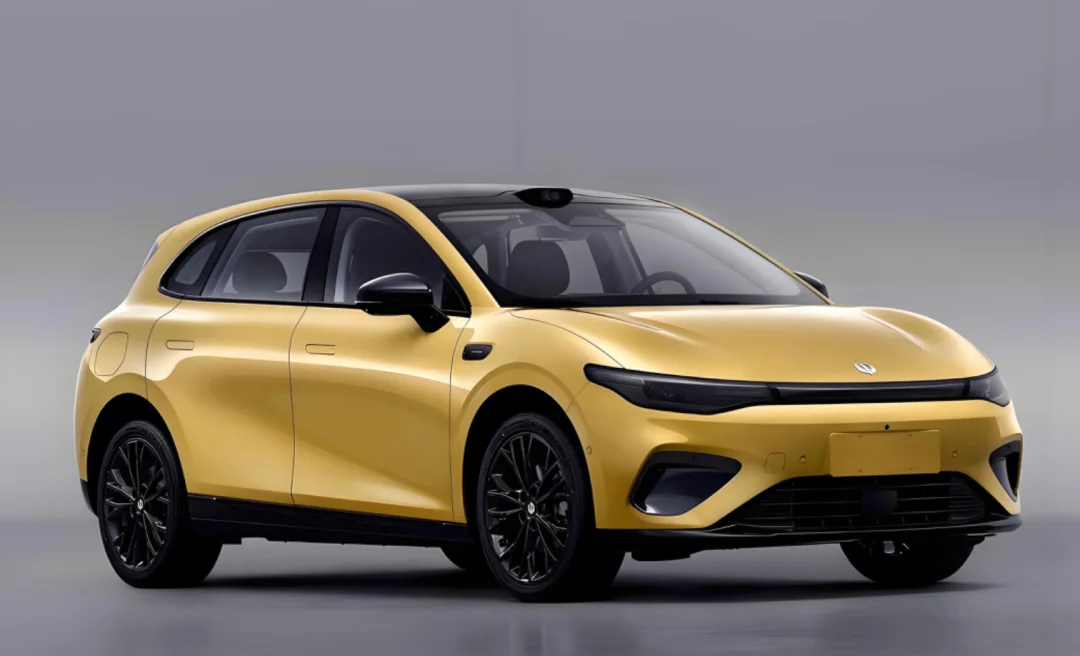
In contrast, Leapmotor accepted investment from Stellantis as early as 2023, and the two parties established a joint venture named Leapmotor International in 2024. Leapmotor Automotive provides product technology, while the Stellantis Group offers global market resources and influence. By binding with Stellantis in terms of capital, products, and channels, Leapmotor has accelerated its entry into markets such as Europe, the Middle East, and South America. Models like the B10 and Lafa5 are now being launched globally, and Leapmotor’s international layout is actually ahead of other new forces—a capability that a follower cannot possess.
These points indicate that Leapmotor is shaping a new growth curve by relying on a mature system of capabilities. Imitation helped it cross the threshold from 0 to 1, but what it must now overcome is the leap from 500,000 units to the million-level, and even up to 4 million units. This step cannot be solved by any form of imitation.
02Why Must Leapmotor Say Goodbye to Imitation?
After announcing its goal of annual sales of one million units next year, Leapmotor revealed a larger target during an interview at this year’s Munich IAA: it aims to become a mainstream global automaker, with the threshold for this status being annual sales of 4 million vehicles.
Zhu Jiangming stated, "Leapmotor's overseas expansion is a long-term strategy; automakers must achieve globalization. The threshold of 4 million units was originally for internal combustion engine vehicles. I believe the threshold for electric vehicles in the future may be even higher, and industry concentration may increase further compared to ICE vehicles."
Then why can't imitation solve the leap from 500,000 to 4,000,000?
First, the competitive logic of the new energy vehicle industry has undergone a fundamental shift. The current market is no longer a contest defined by single products or specific technology routes; it is a comprehensive struggle centered on efficiency, scale, profitability, and globalization.
Whether a company can continuously lower its cost structure, dilute R&D and manufacturing expenses through platformization and high component reuse, and replicate stable supply chain systems across different markets determines whether it remains stuck at a 500,000-unit plateau or gains the potential to leap to a scale of 4 million units.
Leapmotor gained an early foothold in this round of competition largely because it recognized these rule changes earlier than most peers and shifted its focus toward systemic capabilities rather than individual products.
On December 24, 2024, in a company-wide letter marking its ninth anniversary, Zhu Jiangming set four keywords for 2025: brand, technology-driven cost reduction, hit products, and internationalization. All four dimensions were effectively implemented in 2025, with technology cost reduction achieved through self-research and self-manufacturing serving as the foundation and prerequisite for the other three.
In the internal letter released today for the company’s tenth anniversary, Zhu Jiangming emphasized several core capabilities required to challenge the goal of selling one million vehicles annually: continuous technological innovation, extreme quality standards, accelerated expansion into overseas markets, and maintaining an efficient and agile organization. This underscores Leapmotor’s strong emphasis on self-reliant technology development.
Automakers have different paths when it comes to cost reduction. The most direct approach involves cutting configurations or materials. Another relies on leveraging scale advantages to continuously pressure suppliers for lower prices. A third option involves bringing more core processes in-house, reducing long-term costs through self-research and self-production.
Leapmotor chose the third path, keeping more capabilities within its own control.
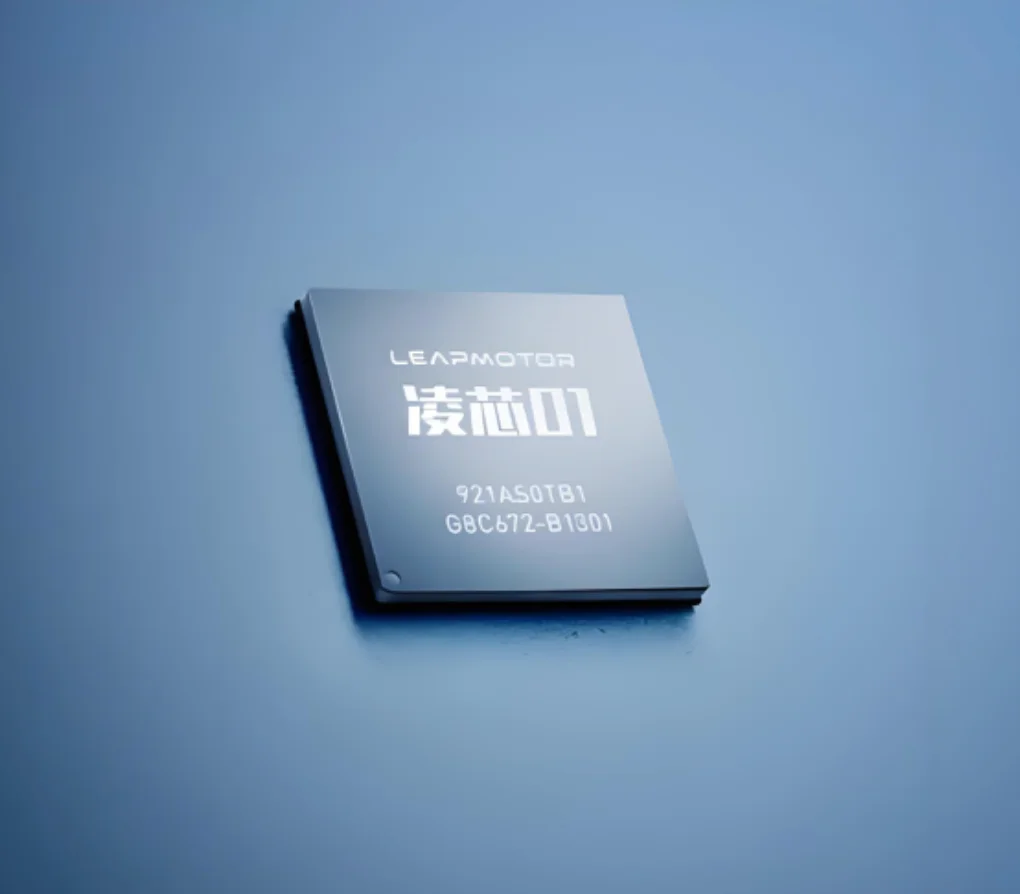
Leapmotor began self-developing core components very early on. The Lingxin 01 autonomous driving chip in its first-generation C11 was jointly developed with Dahua Technology and has since been used in models such as the B10. Zhu Jiangming, before entering the automotive industry, was a co-founder of Dahua Technology. By December 2024, cumulative installations of the Lingxin 01 had exceeded 100,000 units, making Leapmotor one of the few automakers to master autonomous driving chip technology.
Over the past few years, Leapmotor has continuously increased the proportion of self-developed and self-manufactured core parts. Its scope has expanded from battery packs, electric motors, and electronic control systems to controllers within the electronic and electrical architecture, smart cockpit and autonomous driving systems, and high-frequency, high-cost components such as headlights, seats, bumpers, and air conditioning compressors. Currently, Leapmotor’s self-development rate for core components exceeds half. This is a key prerequisite enabling it to equip laser radars in vehicles priced around RMB 120,000 while lowering prices despite continuous configuration upgrades.
Moreover, Leapmotor’s investment in self-development remains highly restrained. Its most critical self-developed areas—batteries, electric drives, and electronic controls—cost only RMB 3.6 billion, less than half of what other new energy vehicle startups spent. In the first half of 2024, Leapmotor’s R&D expenditure was RMB 1.22 billion, representing 43.2% of XPENG’s spending and 20.3% of Li Auto’s.
By September 2025, Leapmotor’s self-development ratio for automobiles had surpassed 65%, higher than NIO’s approximately 50% and XPENG’s 60%. Such a ratio means that cost control, development pace, and pricing power have returned to the automaker rather than remaining with suppliers. On this basis, Zhu Jiangming stated in an interview after the launch of the Lafa 5 in late November: 'Achieving 80% self-development is appropriate; if possible, going even higher would be fine.'
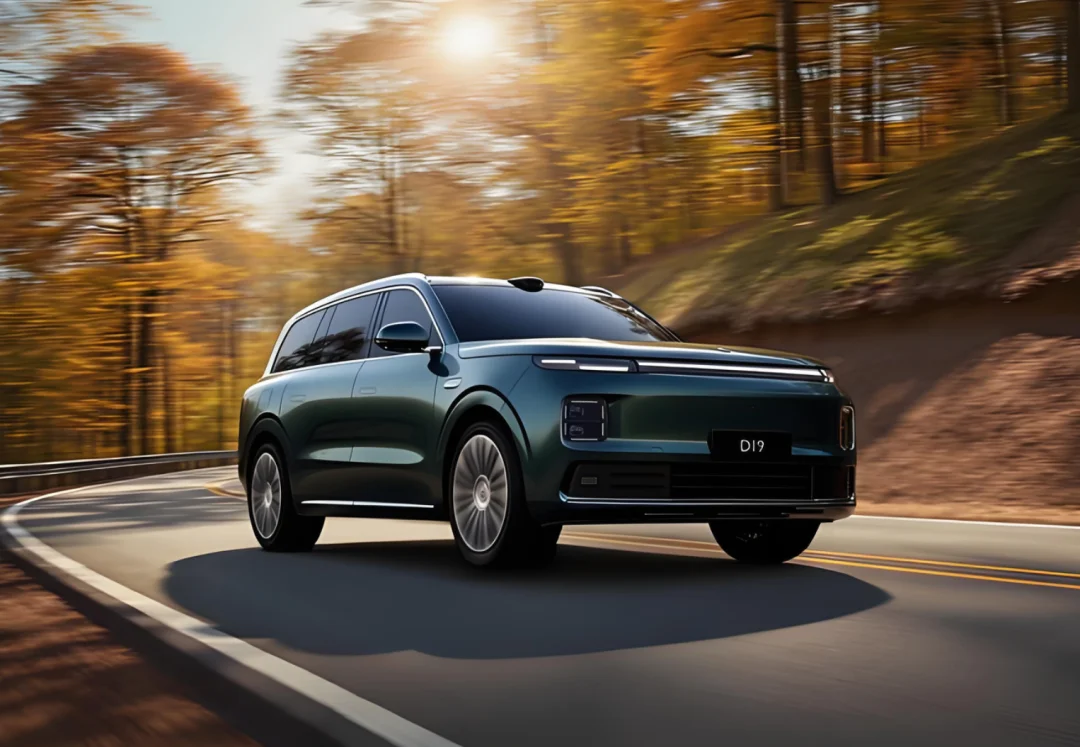
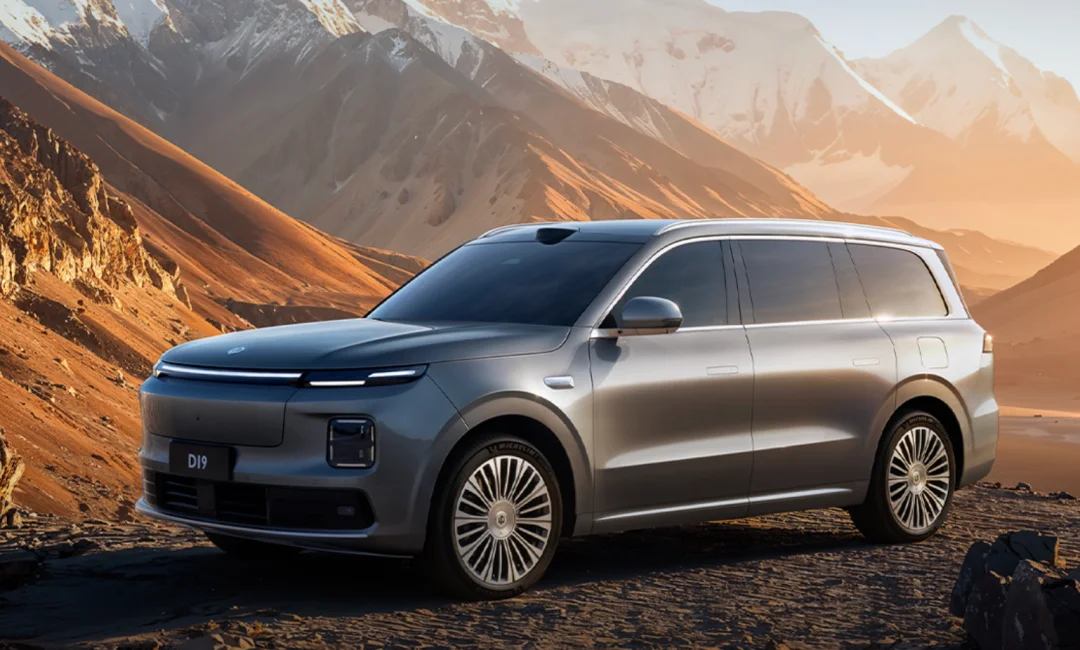
Leapmotor’s platformization is also accelerating rapidly. During the third-quarter earnings call in 2024, Zhu Jiangming revealed that the C10 and C16 share 70%–80% common components. In the first half of this year, Leapmotor launched two new B-platform models and three refreshed C-platform products, followed by the Lafa 5 and D19 in the second half—all built on self-developed technical architectures.
This highly unified architecture directly translates into tangible, quantifiable cost advantages. The more concentrated the platform, the higher the component reuse rate, and the lower the marginal cost. For example, using Leapmotor’s CTC (Cell-to-Chassis) technology, which integrates the battery pack with the chassis structure, reduces the cost per vehicle by nearly RMB 1,500 at once.
The same logic applies to the battery segment. During Leapmotor’s third-quarter earnings call, when asked about rising battery raw material prices, management offered a representative answer: reducing the variety of cell types makes volatility risks manageable during price hikes.
"As Leapmotor's volume increases and we implement scientific planning for cells, our cell variety is very limited. We have achieved excellent platformization across our cells. Although our sales reached approximately 600,000 units this year, our cell variety is far smaller than that of our peers. A narrower range of cell types is a significant benefit for manufacturers, enabling high overall capacity utilization and avoiding frequent line changeovers. This greatly improves production efficiency and lowers manufacturing costs for the cells."
These internal refinements cannot be achieved through simple imitation.
More importantly, once this system is established, the competitive boundary is no longer confined to the domestic market; it naturally possesses the potential to go global. Efficiency, cost, and scale advantages are themselves the most powerful credentials for Chinese new energy vehicle companies in international markets.
On October 23, Zhu Jiangming explicitly stated in an exclusive media interview: "China's new energy vehicle supply chain advantage is already globally leading, not only in complete vehicles but also in all core components, which hold advantages in scale, quality, and cost."
At the same time, continuing to follow Li Auto’s route has gradually become unfeasible. Li Auto encountered growth bottlenecks in its extended-range electric (EREV) strategy starting in 2024. Sales and profitability came under clear pressure in the third quarter of 2025, as the economies of scale for EREV models could no longer expand.
Looking at the broader market, Li Auto’s experience was not an isolated incident but a result of structural changes across the entire industry. Data from the China Association of Automobile Manufacturers shows that in October, retail sales of fuel vehicles in China fell by 10% year on year, while pure electric models grew by 20%. EREV models declined by 7.7%, and plug-in hybrid models dropped by 10.3%. Within the new force sector, the shift in powertrain structure was even more dramatic: the ratio of pure electric to EREV share rapidly widened from 49%:51% last year to 74%:26%.
External market data also confirms this trend. Statistics from Automobility show that although plug-in hybrid models maintained year-on-year growth in absolute shipment volume, their share of the overall new energy vehicle market has declined for several consecutive months, falling below 35%, significantly lower than the peak of over 44% seen in mid-2024.
In other words, the market is increasingly favoring pure electric vehicles, while the room for range-extended and plug-in hybrid models is becoming progressively limited.
Li Auto has also begun rolling out products such as the i8 and i6 this year to complete its pure electric lineup, but this strategic shift still requires time to prove itself. For Leapmotor, continuing along a growth path that relies heavily on a single technology route cannot support larger scale targets; instead, it risks hitting a ceiling prematurely, facing constraints in cost, pace, and product extensibility.
Longer-term pressure stems from the industry landscape itself. The concentration of the new energy vehicle market is accelerating. Foreign media statistics show that BYD’s share of China’s new energy vehicle market remains close to 30%, with the top six automakers controlling more than 60% of sales, and the top ten approaching 80%.
This indicates intensifying Matthew effects, with sales rapidly concentrating among leading players. If an automaker fails to build its own systemic capabilities—unable to consistently launch products across multiple price segments and markets while maintaining profitability—it will easily be squeezed out of its survival space, or even eliminated.
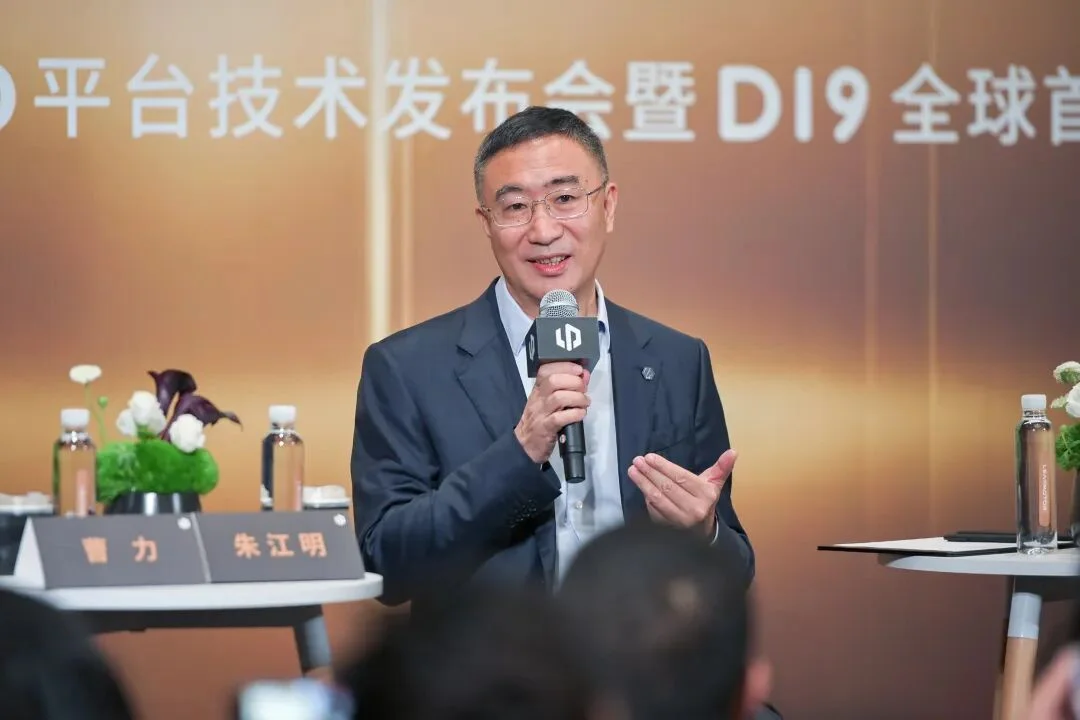
Leapmotor’s internal assessment is that relying on isolated hit models is far from enough; what is needed is long-term scale. In interviews following the Leapmotor D Platform Technology Launch Conference and the global debut of the D19 in October this year, Vice President Cao Li stated: 'Our goal is to become a world-class new energy vehicle company. We aim to achieve this step by step, focusing on long-term development.'
Also during this interview, when Zhu Jiangming was asked what it feels like to be the 'big brother,' he cited Huawei’s Ren Zhengfei to express his perspective: 'I have always turned a blind eye to success; I only see problems and difficulties.' He explained that NIO, XPENG, Li Auto, Neta, and WM Motor have all been number one in sales at various times, experiencing temporary leadership and fierce competition. 'But the automotive industry is a long marathon; who finishes last is not yet certain.'
03From RMB 500,000 to RMB 4 Million: How to Achieve It?
For Leapmotor, which has just achieved an annual sales volume of 500,000 units, setting a short-term target of 4 million units is clearly unrealistic. However, viewing it as a long-term direction that Leapmotor is aligning with helps better understand the company’s recent moves.
In a recent live stream, Zhu Jiangming stated that Leapmotor’s next phase goal is to reach 1 million units in annual sales, with a more distant vision of entering the top ten global automakers, expressing hope to become a major manufacturer like BYD or Geely.
Why does Leapmotor dare to set its target at the million-unit level?
Leapmotor feels confident placing this target on the table because its understanding of growth has shifted from betting on hit models to betting on systemic capabilities. Currently, Leapmotor’s systemic capabilities hold significant potential for cost reduction.
This cost-reduction capability is being continuously amplified through production lines and bases. The newly completed Huzhou components base now possesses production lines for battery packs, electric drives, headlights, power controllers, and other components. For Leapmotor, this means costs are no longer entirely dependent on negotiations with external supply chains but can be actively diluted through internal manufacturing rhythms, platform planning, and scale expansion.
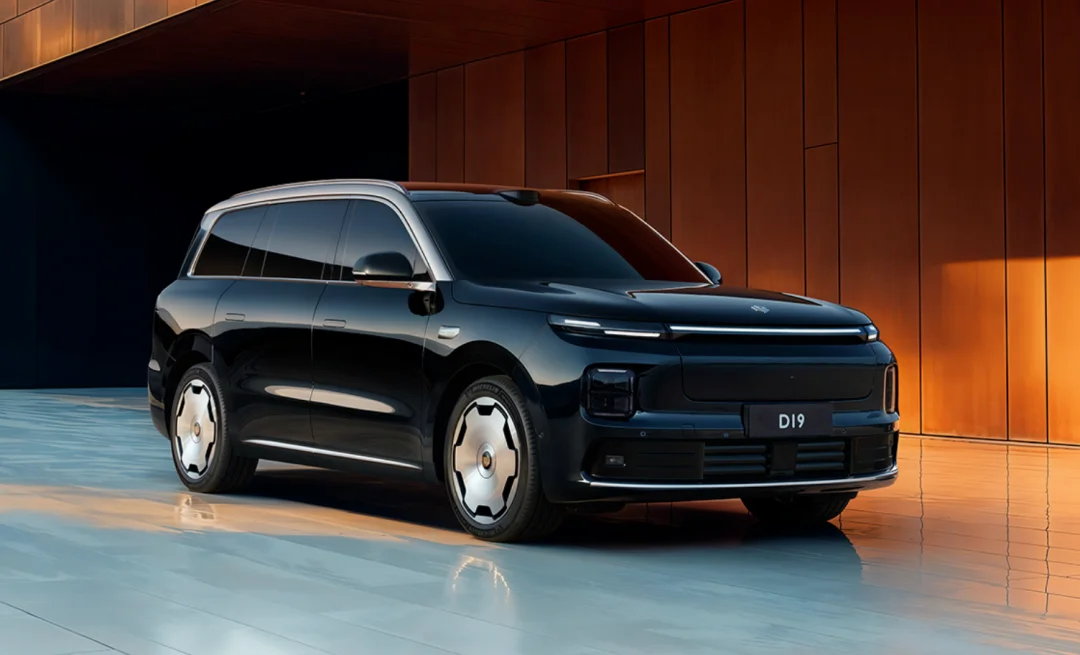
On specific products, this systematic cost-reduction capability is translating into product advantages more smoothly. Taking the D19 extended-range version as an example, its newly introduced integrated drive-and-generator range-extender system directly lowers the vehicle’s BOM (Bill of Materials) cost by reducing the number of parts and system complexity.
Zhu Jiangming once said in an interview, a statement that sparked controversy: 'As costs decrease, it is reasonable for mid-to-large SUVs to eventually sell for 50,000 RMB.' This clearly expresses Leapmotor’s understanding of cost boundaries: as long as efficiency continues to improve, prices have room to drop further.
Beyond the cost structure, Leapmotor is simultaneously adjusting its product mix, using high-end models to subsidize lower-end ones. The baton for enhancing brand value and sales volume has been passed to the D19 and Lafa5. The Lafa5 and D19 assume different roles: the former expands coverage through price concessions, while the latter attempts to validate profitability in higher price segments. During the Q3 earnings call this year, Leapmotor management expressed strong confidence in the D19: 'The pre-order volume for the D series is the largest among all products we have launched pre-orders for within the same timeframe. The D19 will definitely be a product that makes everyone scream.'
Although Leapmotor has paused its "imitation" of product positioning, it has decided to continue following on the technology route rather than being a "lone brave." In fields such as driver assistance that require massive investment and have long return cycles, Leapmotor has chosen a clear "following strategy." Being ahead might waste resources. Following means maximizing efficiency and minimizing costs. Zhu Jiangming’s statement was straightforward: "At this stage, blind leadership does not necessarily bring an efficiency advantage." For Leapmotor, what matters more is transforming technology into hit products at a lower cost and faster pace under a mature route.
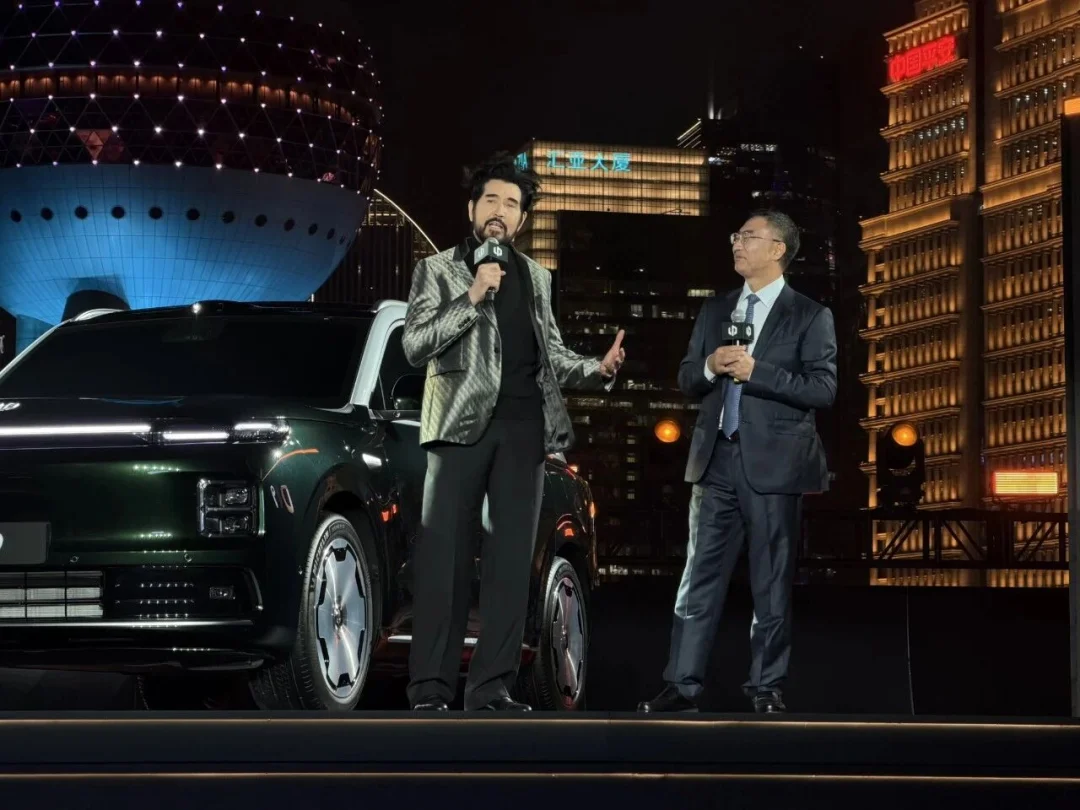
During this period, as the cost structure and product tiers became clearer, Leapmotor gradually shifted its focus more toward "being seen." In the domestic public opinion arena, Leapmotor signed Fei Xiang for the D19, and the brand began pursuing unique emotional value and fresh product routes. Leapmotor executives stated during the Q3 earnings call this year: "The D19 will feature ideas and gameplay beyond current models in brand promotion, channel strategy, and terminal retail, aiming to create products that make people scream. New species will be launched in 2027 or 2028."
Furthermore, going public, introducing Stellantis capital, and advancing localized production in Europe are essentially aimed at lowering the threshold for entering overseas markets. Unlike many Chinese brands that choose to build channels from scratch, Leapmotor directly entered Stellantis’s mature European sales network system through its strategic cooperation with Stellantis.
Surprisingly, the partnership between Leapmotor and Stellantis has produced a reverse effect where the guest acts as the host. Li Tengfei, Vice President of Leapmotor, stated during the Q3 2025 earnings call that, from the new energy sector perspective this year, the overall performance of Stellantis’s own 14 brands was not particularly bright. Among Stellantis’s new energy vehicles, the most outstanding brand was Leapmotor. "Although Leapmotor does not belong to the Stellantis Group, at least our joint venture company overseas is controlled by them. The performance of the Leapmotor brand has actually exceeded the expectations of many leaders within Stellantis. Therefore, both the chairman and CEO of Stellantis now pay more attention to the Leapmotor brand."
In October, Leapmotor received 12,000 orders overseas. Next year, Leapmotor’s overseas sales target is expected to be in the range of 100,000 to 150,000 units.
Meanwhile, Leapmotor’s European manufacturing base has been confirmed to land at the Zaragoza plant in Spain. After renovation, it will first produce B-series models. The B10 is expected to roll off the line in the third quarter of next year, followed by the debut of the B05 at the Munich Motor Show. This model of localized production plus local channel sales is clearly preparing for larger-scale operations, not just testing the waters.
However, all these efforts do not mean that Leapmotor has already stepped onto the fast track to achieving 4 million annual sales and becoming a "world-class automaker." On the contrary, going from 500,000 to 1,000,000 is itself a sufficiently steep threshold. Larger scale means more complex supply chains, higher management requirements, and fiercer global competition.
This road is bound to be difficult. It will test not only product strength but also cost control, organizational capability, and global coordination. It is too early to say whether Leapmotor can truly reach 4 million, but at least one thing is clear: it has not lost its bearings amid this brief moment of success and is preparing for a long and brutal competition.
Written by: Dayong Edited by: James